


Evaluating Regional Semiconductor Manufacturing Clusters Foundry Capacities and Global Processor Allocations
The worldwide development, architectural design, wafer fabrication, and enterprise deployment of microprocessors and graphics processing units exhibit distinct regional characteristics that shape the Microprocessor And Gpu Market Share. Regional market dynamics reflect variations in advanced sub-nanometer cleanroom density, software ecosystem maturity, semiconductor intellectual property ownership, and national industrial funding initiatives. North America holds a dominant position in high-value fabless processor design, software toolchain development, and hyperscale enterprise deployments, generating a major portion of global market value. Concurrently, the physical fabrication of advanced microprocessor and GPU silicon wafers, 3D packaging assembly, and high-volume electronics integration is predominantly centered within specialized microelectronics manufacturing corridors across East Asia.
North America maintains a leading position in microprocessor and GPU architectural innovation, high-performance computing design, and enterprise artificial intelligence platforms. The United States serves as the global corporate and R&D headquarters for prominent microprocessor and GPU innovators, including NVIDIA Corporation, Intel Corporation, Advanced Micro Devices (AMD), Qualcomm Incorporated, and Apple Inc. Furthermore, North American cloud hyperscalers—such as Microsoft, Google, Meta, and Amazon—lead global procurement of server CPUs and data center GPU clusters to support consumer and enterprise AI infrastructure. The region's competitive position is reinforced by federal industrial policies under the CHIPS and Science Act, which provides tens of billions of dollars in subsidies to construct advanced sub-2nm commercial wafer fabrication lines and advanced packaging facilities domestically, mitigating geopolitical supply chain vulnerabilities.
The Asia-Pacific region commands the dominant share of global semiconductor wafer foundry throughput, advanced packaging assembly, and consumer hardware integration. Taiwan, South Korea, Japan, and China represent the world's most concentrated corridor for extreme ultraviolet (EUV) lithography, chemical mechanical planarization, and 3D silicon packaging. Taiwan Semiconductor Manufacturing Company (TSMC) is the essential manufacturing hub for the global processor industry, fabricating high-end GPUs, server CPUs, and mobile SoCs for global fabless designers. In South Korea, Samsung Electronics operates advanced wafer foundries while leading global manufacturing of High-Bandwidth Memory (HBM) modules essential for GPU acceleration. In China, massive domestic consumer electronics assembly, expanding electric vehicle manufacturing, and state-backed investments in domestic semiconductor foundries sustain high consumption of both commercial microprocessors and domestic accelerator designs.
The European market maintains a specialized share anchored in semiconductor photolithography equipment manufacturing, automotive-grade microprocessors, and energy-efficient processor IP design. The Netherlands hosts ASML, the world's sole commercial manufacturer of High-NA Extreme Ultraviolet (EUV) photolithography scanners required to print sub-3nm processor circuits globally. In the United Kingdom, Arm Holdings designs energy-efficient RISC processor architectures that power over ninety-five percent of the world's smartphones and are increasingly deployed in high-efficiency cloud data centers. European semiconductor manufacturers—including STMicroelectronics, Infineon Technologies, and NXP Semiconductors—excel in supplying safety-certified automotive microprocessors and industrial automation processing units, establishing a stable, compliance-focused regional market for high-reliability embedded processors.
Top Trending Reports :
Handheld Thermal Imaging Equipment Market
الأقسام
إقرأ المزيد
Pet arthritis, also known as osteoarthritis, is a common and painful condition that affects dogs, cats, and other companion animals. It occurs when the cartilage protecting the joints deteriorates, leading to pain, stiffness, and reduced mobility. As pets age, the risk of arthritis increases, but it can also affect younger pets due to genetics, injury, or obesity. The market for pet arthritis...

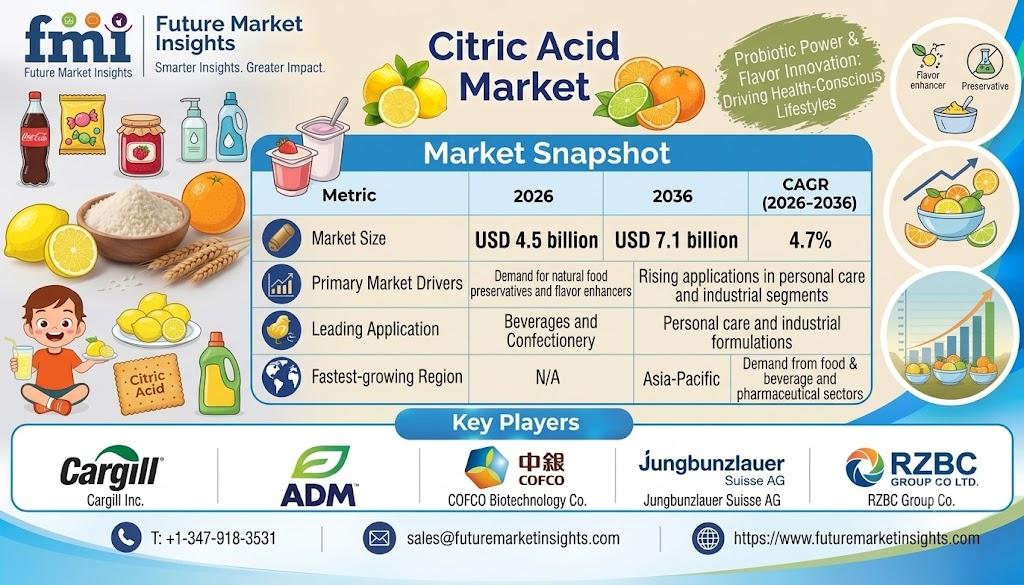
Citric Acid Market Powder Leads Form Category at 45.0% NEWARK, Del., September 25, 2026 According to Future Market Insights (FMI), the Citric Acid Market is projected to grow from sales estimated at USD 4.5 billion in 2026 to USD 7.1 billion by 2036, expanding at a 4.7% CAGR. The market was valued at USD 4.3 billion in 2025. Citric acid remains a widely used ingredient across food and...
A therapeutic class that offers better tolerability than older migraine drugs and a mechanism targeted at the disease's root cause should be growing faster than the low double digits. The CGRP antagonist market faces structural constraints that limit its reach, and understanding them is essential for stakeholders navigating the CGRP inhibitor market . Cost and Payer Access Barriers The primary...
Healthcare smart card readers are devices that read and authenticate smart cards used for patient identification, secure access, and payment processing. In an era of rising data breaches and regulatory pressure, these readers are becoming essential for protecting sensitive health information. The global healthcare smart card reader market is growing as providers upgrade security...
Streamlining high-volume bicarbonate concentrate preparation in clinical renal care units is expanding global adoption across the Hemodialysis Dry Powder Bag Market. Dry powder bags containing sodium bicarbonate and essential electrolytes are connected directly to automated hemodialysis machines, reconstituting online into sterile liquid dialysate during patient treatment sessions. Utilizing...