Well Stimulation Materials and Chemicals Market to Hit $27.7B
The well stimulation materials and chemicals market covers the proppants, completion fluids, treatment chemicals, and perforating equipment injected into a wellbore to improve the permeability and productivity of a hydrocarbon reservoir. According to Market Research Future, the market was valued at USD 19.97 billion in 2024 and is projected to reach USD 27.7 billion by 2035, expanding at a compound annual growth rate of 3.02%. That rate reflects a market tied to the operating expenditure of existing fields rather than to exploration cycles: as energy companies seek to optimize production from existing wells, the utilization of advanced stimulation materials has become paramount.
Report Key Statistics
Insights published by Market Research Future reveal a market segmented by product type, application, extraction method, and company size. By product type, proppants hold the largest share, valued at USD 5.99 billion in 2024, primarily due to their critical role in enhancing oil and gas production by keeping fractures open and ensuring permeability. Completion fluids are projected to grow from USD 4.5 billion in 2024 to USD 6.1 billion by 2035, stimulation chemicals are projected to grow from USD 3.0 billion to USD 4.0 billion and represent the fastest-growing product category as specialized formulations designed to improve fluid behaviour and increase production yields gain traction, and perforating guns and other stimulation materials contribute the remainder.
By application, oil wells secure the largest market share and are projected to reach USD 10.5 billion by 2035, driven by the continuous need for enhanced oil recovery and production efficiency with established infrastructure and persistent demand for stimulation materials. Gas wells are the fastest-growing segment, driven by increasing demand for natural gas and reflecting both technological advancements in gas extraction and a shift toward cleaner energy solutions. Geothermal wells and other applications hold smaller positions.
By extraction method, hydraulic fracturing is the dominant technique, significantly outpacing other practices in volume and adoption across various oil and gas reservoirs, and is projected to reach USD 10.5 billion by 2035. Acid stimulation is smaller in share but gaining traction as operators look to enhance extraction efficiency in mature fields, with growth driven by a shift towards optimizing well performance and reducing operational costs, and by the increasing focus on environmental sustainability that favours methods minimizing water usage. Nitrogen injection, CO2 injection, and other methods complete the segmentation.
By company size, large companies dominate, commanding the largest share due to extensive resources and established client relationships, with robust supply chains enabling efficient operation and the ability to meet the demands of large-scale projects. Small companies hold a smaller share but are gaining traction rapidly, growing from USD 3.99 billion in 2024 to USD 5.5 billion by 2035, due to their ability to innovate and adapt to the specific needs of customers, leveraging niche markets and personalized services.
Regionally, North America accounts for approximately 45% of the global market share, driven by increasing demand for oil and gas coupled with advancements in hydraulic fracturing technologies, with the United States and Canada the primary contributors and significant investments in shale gas exploration and production. Europe holds approximately 25% of the global market share with Norway and the UK leading, shaped by regulatory frameworks aimed at enhancing energy efficiency and reducing carbon emissions and by the European Union's Green Deal. Asia-Pacific accounts for approximately 20% of the global share, fuelled by increasing energy demands particularly in China and India where urbanization and industrialization are driving oil and gas exploration. The Middle East and Africa contribute approximately 10%, with vast oil and gas reserves particularly in Saudi Arabia and Nigeria driving demand.
Industry Trends
Findings from Market Research Future identify three trends reshaping the market. First, sustainability initiatives are prompting companies to prioritize eco-friendly materials and practices to comply with stringent regulations, and this suggests a growing emphasis on developing biodegradable proppants and non-toxic chemical agents. Second, technological advancement in material science is significantly impacting the market, with the introduction of high-performance proppants and specialized chemical formulations appearing to improve the efficiency of stimulation processes and potentially leading to enhanced recovery rates and reduced operational costs. Third, the increased demand for enhanced oil recovery is driving consumption: as conventional reserves deplete, operators are increasingly turning to EOR methods requiring specialized stimulation materials, and the market for EOR is projected to grow at a compound annual growth rate of over 10%, accompanied by increased demand for the materials that support these methods.
Challenges
The market's growth path involves real friction. The 3.02% CAGR is modest, meaning share gains must come from displacing competing technologies or suppliers rather than from market expansion alone. Regulatory frameworks are becoming more stringent, compelling companies to adopt sustainable practices and materials, which raises formulation cost and qualification time for new chemistries. Water usage and disposal associated with hydraulic fracturing attract scrutiny that varies by jurisdiction, creating compliance complexity across regions. Raw material pricing for proppant feedstocks and chemical intermediates affects margins on long supply chains. And the shift toward acid stimulation in mature fields requires different material sets and technical expertise than the fracturing work that dominates current volumes.
Future Outlook
Analysis presented by Market Research Future identifies several opportunities. Development of eco-friendly stimulation materials for sustainable practices aligns with the sustainability trend and with operator commitments to reduce environmental footprint. Investment in advanced data analytics for optimized stimulation processes aligns with the digitalization of oilfield operations and with the introduction of smart materials that can adapt to downhole conditions, which recent studies suggest can increase recovery rates by up to 20%. Expansion into emerging markets with untapped oil and gas reserves aligns with Asia-Pacific's position as the fastest-growing region. Rising energy demand provides the foundation, with the International Energy Agency projecting global energy demand to rise by 30% by 2040, necessitating advanced well stimulation techniques.
Expert Discussion
Industry practitioners describe a dynamic competitive landscape driven by technological advancements and increasing demand for efficient extraction methods. Halliburton, Schlumberger, Baker Hughes, Weatherford International, National Oilwell Varco, C&J Energy Services, Trican Well Service, Calfrac Well Services, and Pioneer Energy Services are the principal players, each adopting distinct strategies. Halliburton emphasizes innovation in hydraulic fracturing technologies, and in August 2025 announced a strategic partnership with a leading technology firm to develop advanced AI-driven solutions for real-time monitoring of well stimulation processes, poised to enhance operational efficiency and reduce costs. Schlumberger focuses on digital transformation and data analytics to optimize well performance, and in September 2025 launched a new suite of digital tools aimed at enhancing the efficiency of hydraulic fracturing operations, enabling clients to access real-time data analytics and predictive modelling. Baker Hughes is actively pursuing sustainability initiatives, integrating eco-friendly materials into stimulation processes, and in July 2025 unveiled a new line of environmentally friendly stimulation materials designed to minimize ecological impact during extraction. Companies are localizing manufacturing and optimizing supply chains to respond swiftly to market demands, and the market appears moderately fragmented with a mix of established players and emerging companies. As of October 2025, competitive trends are increasingly defined by digitalization, sustainability, and the integration of artificial intelligence, with competitive differentiation likely to evolve from traditional price-based competition to a focus on technological innovation, supply chain reliability, and sustainable practices.
Conclusion
The well stimulation materials and chemicals market is positioned for steady growth, supported by the imperative to extract more from existing wells and by the shift toward gas as a lower-carbon fuel. Emerging opportunities lie in biodegradable proppants, non-toxic chemical formulations, and data-driven stimulation optimization. Technological development will focus on smart materials responsive to downhole conditions, formulation efficiency, and the monitoring capability that reduces treatment uncertainty. The long-term outlook is one of reliable, production-linked demand with gradual premiumization as sustainability requirements enter procurement criteria. Where capital-intensive infrastructure markets such as the US Water Desalination Market are shaped by plant construction, well stimulation materials are consumed in the operating budget of every producing well, which makes their demand closely coupled to production targets rather than to capital cycles.
Kategorien
Mehr lesen
Market share analysis in the oil and gas separators sector reveals a competitive landscape where established application leaders retain dominance while water separation and midstream end uses reshape positioning. Based on Market Research Future's assessment, the Oil & Gas Separators Market Share is distributed across a market estimated at USD 0.08 million in 2024 and projected to reach USD...
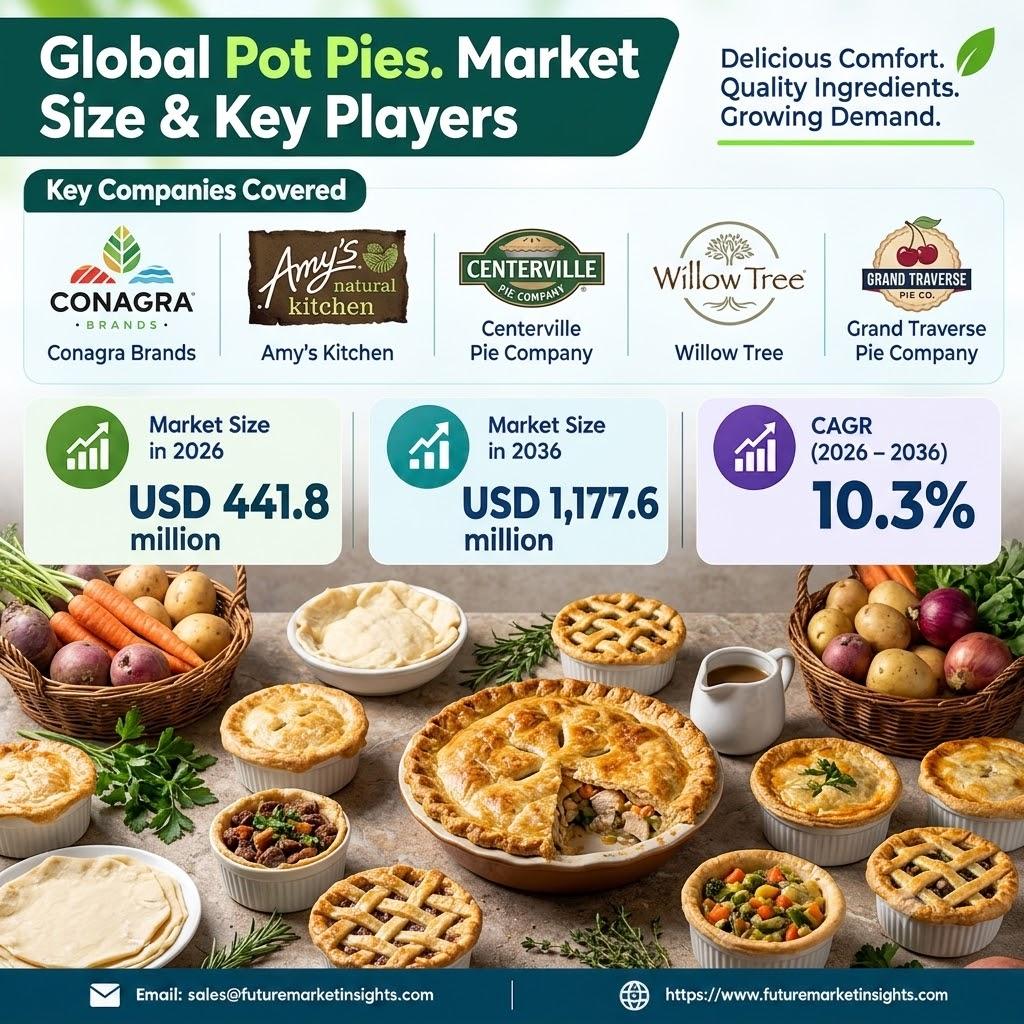
Pot Pies Market Demand for Convenient Meals Increases NEWARK, Del., October 26, 2026 — The global pot pies market is gaining momentum as food manufacturers, frozen meal producers, retailers, and foodservice operators respond to demand for convenient, ready-to-prepare savory meals. According to the latest market intelligence report published by Future Market Insights (FMI), the global pot...
Market Overview The blepharitis market is being shaped by novel therapies and future directions, including new anti-inflammatory agents, microbiome modulation, and advanced diagnostics. The market is projected to grow through 2030, driven by growing research and unmet needs. Ophthalmology clinics and research institutions are increasingly collaborating on clinical trials. Growing adoption of...

Monoclonal antibodies have transformed cancer treatment by targeting specific proteins and pathways involved in tumor growth or immune regulation. As the patents of major biologic medicines expire, biosimilar versions are creating new competition in oncology. The Oncology Biosimilars Market is forecast to grow from USD 5.469 billion in 2024 to USD 14.4 billion by 2035. Monoclonal antibodies...
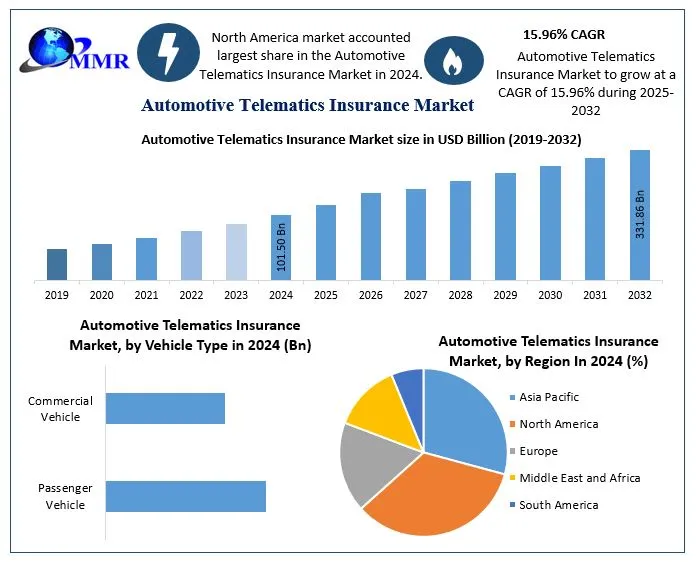
Market Overview The Automotive Telematics Insurance Market is entering a period of strong expansion as insurers increasingly use connected-vehicle data, artificial intelligence (AI), Internet of Things (IoT) technologies, smartphones, and real-time analytics to develop personalized insurance products. According to Maximize Market Research, the global Automotive Telematics...