


Evaluating Regional Semiconductor Innovation Hubs, Global Foundry Ecosystems, and DSP Market Share Allocations
The worldwide development, precision architecture design, compiler toolchain engineering, and commercial deployment of digital signal processors exhibit distinct regional characteristics that shape the Digital Signal Processors (DSP) Market Share. Regional market dynamics reflect variations in localized semiconductor fabless design talent, commercial pure-play foundry cleanroom capacity, consumer electronics manufacturing density, and automotive active-safety regulations. High-value DSP microarchitecture intellectual property, advanced vector compiler toolchains, and multi-core baseband processor designs are heavily centered across specialized semiconductor conglomerates in North America and Western Europe. Simultaneously, the large-scale physical manufacturing, surface-mount PCB assembly, and commercial end-market integration of DSP silicon into smartphones, automotive vehicles, and telecommunications base stations are concentrated within specialized manufacturing corridors across East Asia, establishing an interconnected global microelectronics supply chain.
North America maintains a dominant position in digital signal processor market revenues, architectural intellectual property ownership, and aerospace-defense signal processing innovations. The United States serves as the corporate, research, and design headquarters for several global DSP pioneers, most notably Texas Instruments (TI), Analog Devices Inc. (ADI), Qualcomm Incorporated, and Cirrus Logic, alongside specialized processor IP developers such as Cadence Design Systems (Tensilica) and CEVA Inc. Texas Instruments and Analog Devices established the foundational global benchmarks for standalone general-purpose and floating-point DSPs (such as TI’s TMS320 family and ADI’s SHARC and Blackfin architectures), which remain deeply entrenched across industrial automation, audio consoles, and medical instrumentation. Furthermore, North American fabless innovators (such as Qualcomm with its Hexagon DSP architecture) lead the global market in embedding advanced DSP cores into mobile application processors and 5G modems. North American demand is heavily underpinned by continuous defense aerospace procurement for radar electronic warfare systems, 5G wireless carrier investments, and consumer electronics design, sustaining steady high-margin revenues.
The Asia-Pacific region commands the dominant share of global DSP physical silicon consumption, consumer electronics packaging assembly, and rapid automotive electronics adoption. China, Japan, South Korea, and Taiwan represent the world's most concentrated corridor for consumer smartphone assembly, 5G telecommunications base station manufacturing, and automotive electric vehicle production. In Taiwan, premier pure-play semiconductor foundries (most notably TSMC) process millions of advanced silicon wafers annually for global fabless DSP designers, fabricating advanced sub-7nm and 5nm DSP-integrated SoCs. In Japan, pioneering optoelectronic and consumer electronics giants (such as Sony, Yamaha, and Renesas Electronics) lead the global market in deploying specialized audio and image signal processors (ISPs) across professional studio soundboards, digital cameras, and automotive ADAS vision systems. In China, massive state-backed investments in domestic semiconductor self-sufficiency have accelerated the growth of domestic fabless DSP and baseband design firms, supplying domestic 5G telecommunications infrastructure and automotive assembly lines. Furthermore, expanding consumer electronics manufacturing corridors across India and Southeast Asia sustain high regional demand for low-cost audio and sensor DSPs, cementing Asia-Pacific as an indispensable volume driver of global industry growth.
The European market maintains a specialized share shaped by world-leading automotive powertrain and safety engineering, industrial robotics automation, and telecommunications infrastructure excellence. European nations, led by Germany, Switzerland, the United Kingdom, and the Netherlands, host leading automotive semiconductor conglomerates, most notably NXP Semiconductors, STMicroelectronics, and Infineon Technologies. European chipmakers specialize in integrating automotive-qualified DSP cores into advanced radar front-ends (77 GHz radar transceivers), body acoustics controllers, and motor inverter controllers certified to strict ISO 26262 functional safety standards. In telecommunications, European infrastructure giants (such as Ericsson and Nokia) invest heavily in custom DSP silicon to power 5G massive MIMO base stations. European commercial deployments prioritize high reliability, energy efficiency, and compliance with stringent environmental directives, establishing a stable, quality-focused regional market for industrial-grade and automotive signal processing silicon.
Top Trending Reports :
Carbon Credit Management Services Market
Cargo Handling And Port Services Market
Car Wrapping And Graphics Services Market
Κατηγορίες
Διαβάζω περισσότερα
According to Market Research Future, Electric Mining Truck Manufacturers are at the forefront of transforming the mining industry through innovative electric haulage solutions. These manufacturers combine advanced battery technology, electric drivetrains, and smart systems to deliver trucks that meet demanding mining requirements while reducing environmental impact. Leading Manufacturers...
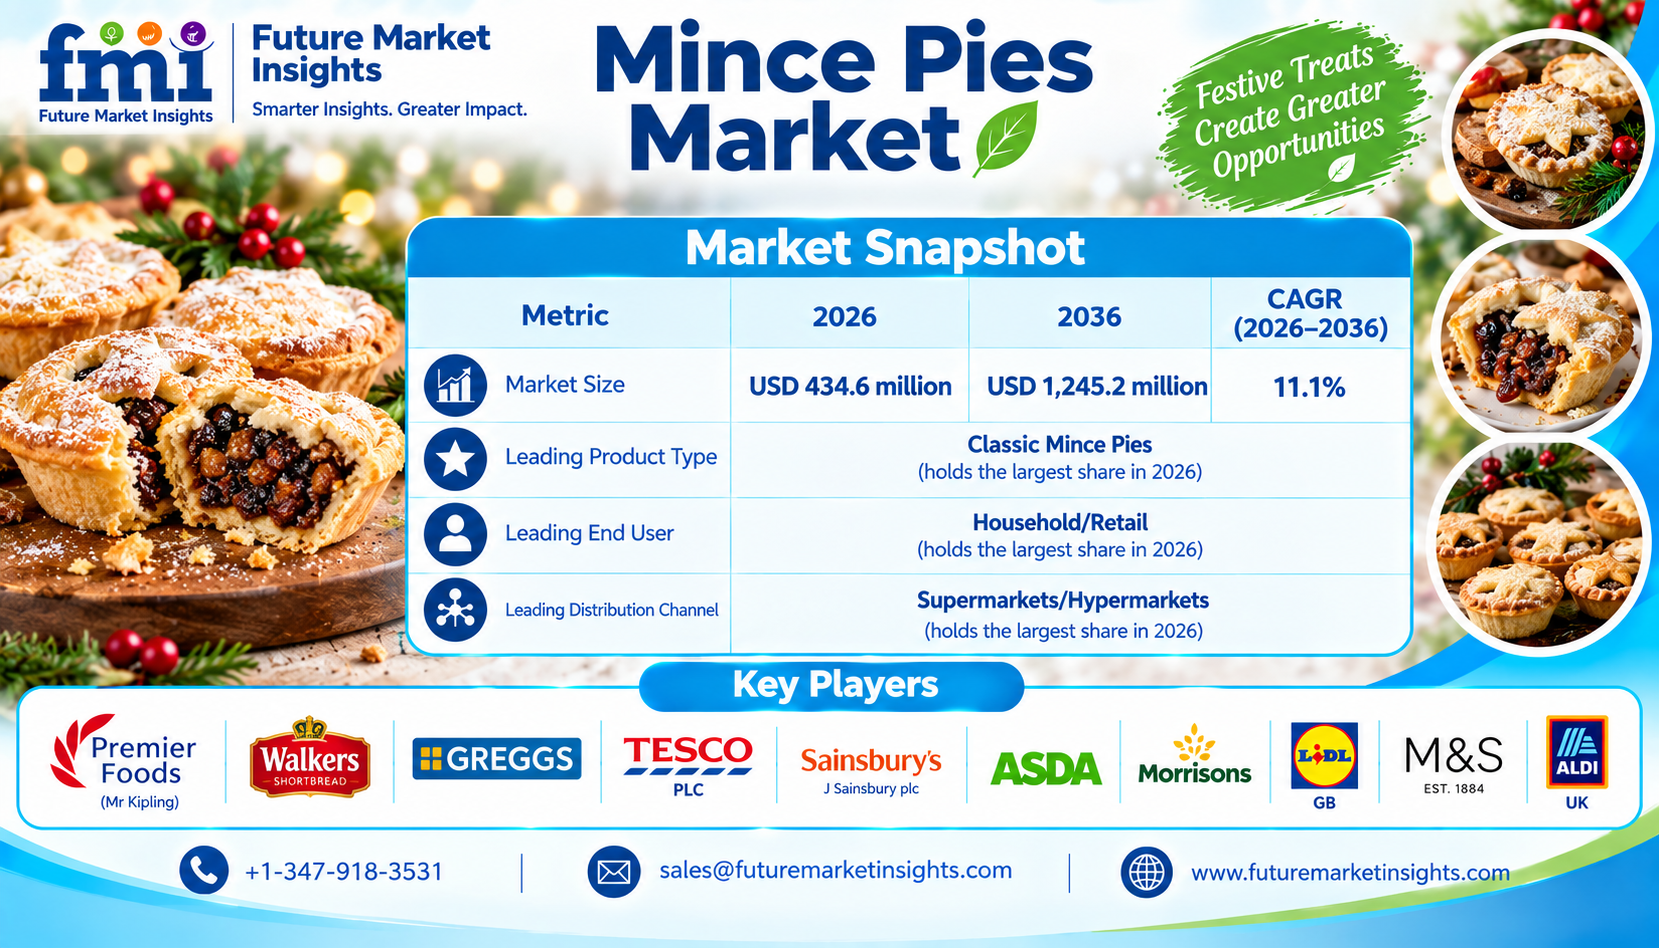
Mince Pies Market as Seasonal Demand and Premium Pastry Variants Extend Festive Consumption The global Mince Pies Market is projected to grow from USD 434.6 million in 2026 to USD 1,245.2 million by 2036, advancing at an 11.1% CAGR during the forecast period, according to the latest research from Future Market Insights (FMI). The market is supported by continued consumer demand for traditional...
The global Vibrating Mesh Nebulizer market is growing as healthcare facilities invest in advanced drug delivery devices to improve patient outcomes and treatment efficiency. The market was valued at USD 0.7467 billion in 2024 and is projected to reach USD 1.567 billion by 2035, growing at a CAGR of 6.97%. The Vibrating Mesh Nebulizer Market includes portable, tabletop, handheld product types,...

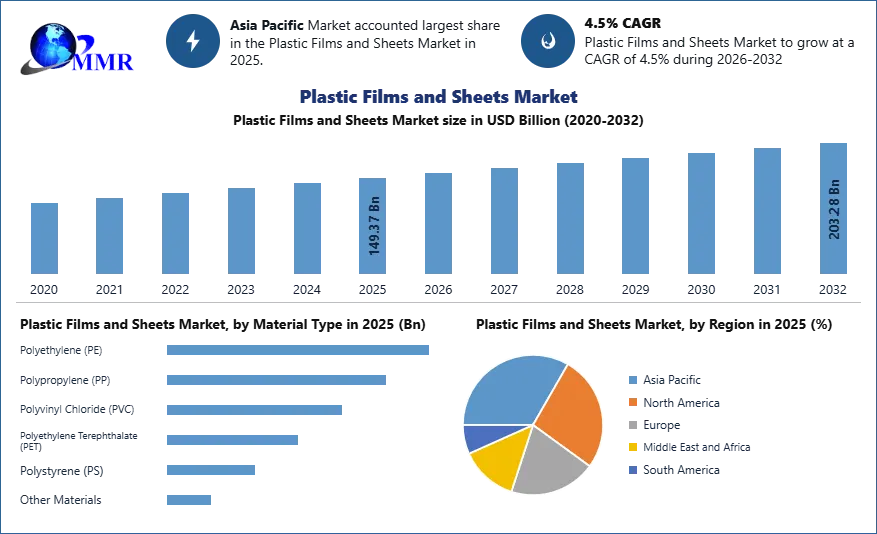
Market Overview The Plastic Films and Sheets Market is witnessing steady growth, supported by rising demand for flexible packaging, food preservation, pharmaceutical packaging, agricultural applications, and industrial protection. According to Maximize Market Research, the market was valued at USD 149.37 billion in 2025 and is projected to reach approximately USD 203.28 billion by...
Market Overview Novel GABA modulators are reducing dependence risk in the anxiolytic market by providing anxiolytic efficacy through allosteric modulation mechanisms that avoid benzodiazepine-associated tolerance, dependence, and withdrawal. These next-generation agents target specific GABA receptor subtypes responsible for anxiolysis while sparing those mediating dependence. The Anxiolytic...