Comprehensive Value Chain Analysis Evaluates Panel Architecture Across Display Verticals
A comprehensive LCD Panel Market Analysis reveals an integrated global manufacturing ecosystem connecting specialty chemical refiners, precision glass substrate fabricators, semiconductor foundry equipment builders, display module assemblers, and consumer hardware brands. At the foundational layer of this value chain are raw material suppliers producing ultra-flat borosilicate glass substrates (Corning, AGC Inc., Nippon Electric Glass), liquid crystal chemical mixtures (Merck KGaA, JNC Corporation), optical polarizing films (Nitto Denko, Sumitomo Chemical), and optical polyester films. The intermediate manufacturing tier comprises specialized panel fabricators operating multi-billion-dollar fabrication plants (Generation 8.5 to Generation 10.5 fabs) that execute thin-film transistor photolithography, color filter deposition, liquid crystal injection, and module bonding. Component suppliers provide driver ICs, timing controllers (T-CONs), and LED backlight units (BLUs). Display module assemblers package these elements into finished open-cell panels or complete display modules. Finally, global television manufacturers, computer monitor brands, automotive Tier-1 integrators, and smartphone OEMs integrate completed LCD panels into consumer and commercial devices distributed worldwide.
From a panel type perspective, the market is broadly segmented into In-Plane Switching (IPS), Vertical Alignment (VA), Twisted Nematic (TN), and hybrid self-emissive/LCD categories. IPS panels dominate the market, capturing the largest share of total market valuation, valued within robust segments ranging from 20.0 to 80.0 USD Billion across major panel types. IPS panels are widely favored across computer monitors, enterprise laptops, smartphones, and professional creative displays due to their superior off-axis viewing angles, color reproduction, and structural stability under touch pressure. Vertical Alignment (VA) panels represent the second-largest and critical panel segment, widely deployed across living room televisions and curved gaming monitors where high native static contrast ratios (typically 3,000:1 to 5,000:1) and deep black levels are prioritized. Twisted Nematic (TN) panels maintain a presence in cost-sensitive entry-level displays and competitive esports monitors, valued for fast native pixel response times and economical manufacturing costs.
Key LCD Panel Value Chain and Manufacturing Stages:
-
Upstream Materials Sourcing: Procuring ultra-flat glass mother glass, optical polarizers, liquid crystal chemicals, and LED chips.
-
Array Process (TFT Backplane): Photolithography, etching, and thin-film deposition forming millions of microscopic transistors on the glass substrate.
-
Color Filter (CF) Process: Depositing red, green, and blue pigment matrices on the upper glass substrate with black matrix light-shielding grids.
-
Cell Process: Precision alignment layer rubbing, spacer dispersion, liquid crystal vacuum injection, and ultraviolet epoxy hermetic sealing.
-
Module Assembly (LCM): Bonding driver ICs (COF/COG), attaching timing controller boards, and integrating LED/Mini-LED backlight units.
-
Final Quality and Optical Inspection: Testing for dead pixels, luminance uniformity, color chromaticity, and panel packaging into shipping crates.
From a display size perspective, the market is categorized into screen sizes below 10 inches, 10–20 inches, 20–30 inches, and 30 inches and above. The 20–30 inches segment represents the largest market share by valuation, capturing significant global spending as desktop monitors, medical displays, and professional workstations standardize within this screen corridor. However, the 10–20 inches segment represents the fastest-growing category by compound annual growth rate, propelled by high-volume laptop upgrades, expanding tablet adoption, and the proliferation of 12- to 17-inch automotive cockpit screens. Screen sizes of 30 inches and above generate major revenue volume, driven by living room televisions and commercial digital signage video walls. By resolution, 1920x1080 (Full HD) holds the largest baseline volume, while 3840x2160 (4K UHD) represents the fastest-growing resolution tier, expanding rapidly toward high-end 7680x4320 (8K) premium displays.
A regional examination indicates clear geographic concentrations in manufacturing capacity, technological design, and consumer end-market consumption. The Asia-Pacific region dominates global consumption and panel manufacturing, holding the vast majority of global production capacity. This dominant position is anchored by massive Generation 8.5 to 10.5 fabrication facilities in mainland China, Taiwan, South Korea, and Japan, led by manufacturing hubs in Shenzhen, Hefei, Wuhan, and Tainan. North America represents a primary technology adoption and consumer consumption market, leading in demand for large-format 4K/8K televisions, premium Mini-LED gaming monitors, and automotive displays. Europe represents a strong secondary consumption market characterized by high demand for energy-efficient displays, industrial automation interfaces, and luxury automotive digital cockpits.
Despite strong market drivers, the LCD panel sector must navigate several structural challenges to maintain long-term profitability. Periodic cyclical imbalances between global fab manufacturing capacity and consumer electronic demand can lead to price drops for open-cell panels, compressing gross profit margins for panel fabricators. Furthermore, rising electricity tariffs and environmental carbon emissions regulations require panel foundries to implement sustainable, cleanroom energy-conservation measures. Leading display manufacturers navigate these hurdles by shifting production capacity toward high-value, customized niches—such as high-margin automotive displays, medical monitors, and ultra-large 85-inch+ television panels—while closing older, inefficient low-generation fabs. By combining manufacturing scale with Mini-LED optical integration and advanced oxide backplanes, premier LCD panel providers continue to defend their operating profit margins and expand their global customer base.
Top Trending Reports :
India Cold Chain Monitoring Market
Italy Cold Chain Monitoring Market
South Korea Cold Chain Monitoring Market
Categorie
Leggi tutto
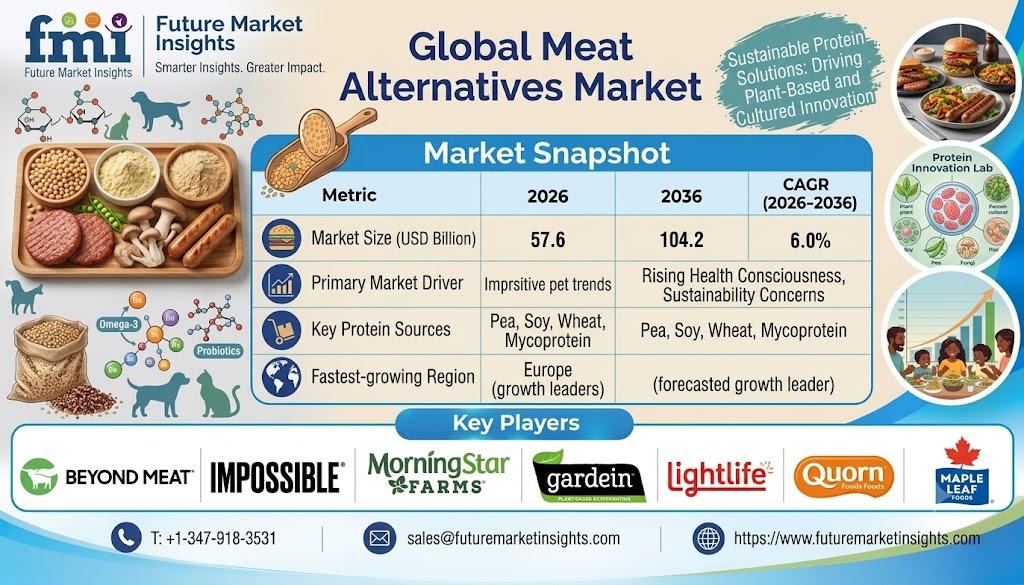
Meat Alternatives Market Tofu Leads Product Type at 60.0% The global meat alternatives market is forecast to increase from USD 57.6 billion in 2026 to USD 104.2 billion by 2036, expanding at a 6.0% CAGR during the 2026–2036 forecast period, according to Future Market Insights. The market was valued at USD 54.3 billion in 2025. Demand is expanding as consumers seek more protein choices...
Pregnancy testing has become faster, cheaper, and more accessible than ever, thanks in part to HCG pregnancy test strips. Unlike bulky midstream tests, strips are simple dip-and-read devices that detect human chorionic gonadotropin in urine. They are inexpensive, compact, and widely available online and in stores. For women who want to test early, test frequently, or simply save money, strips...
Trench fever is one of many vector-borne diseases — illnesses transmitted by organisms such as mosquitoes, ticks, fleas, and lice. These diseases affect millions worldwide and are influenced by climate, urbanization, and social conditions. Understanding how vector-borne diseases spread helps prevent and treat them. Vector-borne diseases include malaria, dengue, Lyme disease, and typhus,...
Market Overview The custom antibody market is being transformed by artificial intelligence platforms that accelerate antibody discovery and design. AI algorithms predict antibody structures, optimize binding affinity, and design novel sequences, compressing development timelines. The Custom Antibody Market is projected to grow through 2035, with AI representing a transformative technology....
The Cardiovascular Information System Market is expanding as hospitals and cardiovascular clinics adopt integrated digital platforms to manage cardiac imaging, monitoring, clinical decisions, patient records, and treatment workflows. According to Wise Guy Reports, the Cardiovascular Information System Market was valued at USD 3.56 billion in 2024 and is expected to reach USD 6 billion by 2035,...