Artificial Intelligence Risk Modeling and Open Banking Financial Pipelines Reshaping Modern Loan Origination
The consumer automotive lending sector is undergoing an operational evolution, shifting from rigid, manual loan underwriting desks toward intelligent, automated lending platforms that leverage the latest auto loan market trends to approve loans in seconds, price risk accurately, and reduce lending fraud. Auto lenders face complex underwriting challenges: economic volatility, changing used-car wholesale values, and subtle income misrepresentations that slip past traditional credit checks during busy retail sales events. Today's modern lending platforms deploy deep-learning credit default predictions, automated open banking data extraction, and machine-learning collateral valuation engines directly within the credit intake workflow, transforming auto financing from a slow administrative barrier into an agile digital sales accelerator.
A defining technological development in the sector is the integration of open banking APIs for automated borrower income and expense verification. Historically, loan applicants had to find paper pay stubs, print bank statements, and provide employment tax forms, which loan officers reviewed by hand—a process that took days and introduced opportunities for document forgery. Modern digital auto lending platforms allow borrowers to link their primary checking accounts securely through standardized open banking connectors. In seconds, the lending software analyzes verified banking transactions, categorizing recurring payroll deposits, tracking rent and mortgage outflows, and identifying undisclosed debt obligations. This real-time cash flow analysis calculates a borrower’s true debt-to-income capacity accurately, enabling lenders to extend instant loan approvals to qualified buyers while identifying fraudulent applications early.
+-----------------------------------------------------------------------------------------+
|                  MODERN DIGITAL AUTO LOAN PLATFORM ARCHITECTURE                         |
+---------------------+-------------------------------------------------------------------+
| USER INTERFACE TIER | Consumer Web Configurator | Dealer Mobile App | Embedded POS Widget|
+---------------------+-------------------------------------------------------------------+
| INTELLIGENCE TIER   | AI Credit Risk Predictor | Machine-Learning Collateral Valuation   |
+---------------------+-------------------------------------------------------------------+
| VERIFICATION LAYER  | Open Banking API Connectors | Biometric Identity & KYC Engine     |
+---------------------+-------------------------------------------------------------------+
| INTEGRATION TIER    | Dealership Management Systems (DMS) | Credit Bureau Gateways      |
+---------------------+-------------------------------------------------------------------+
| LOAN ENGINE TIER    | Dynamic Pricing Engine | Automated E-Contracting | Lien Registry  |
+---------------------+-------------------------------------------------------------------+
| SERVICING & PAYMENTS| Automated ACH Clearing | Digital Payment Gateway | Portfolio Tracking|
+-----------------------------------------------------------------------------------------+
Another major operational trend is the deployment of machine learning algorithms for real-time collateral vehicle valuation and residual forecasting. Because an auto loan is backed by a depreciating physical asset, estimating the vehicle's true market value is critical for calculating accurate loan-to-value (LTV) ratios. Modern valuation engines take in daily transaction records from wholesale auto auctions, retail dealership listings, and regional supply indices, adjusting vehicle values dynamically based on mileage, trim packages, localized market demand, and historical accident records. When evaluating loan applications for used cars, the system determines the vehicle's collateral liquidation value instantly, ensuring lenders avoid over-advancing capital on over-priced vehicles and protecting balance sheets against collateral shortfalls if repossession occurs.
Paperless e-contracting and automated electronic signature execution complete the modern lending paradigm. Once an auto loan is approved, the platform generates complete digital loan contracts, Truth-in-Lending disclosures, and promissory notes. The borrower reviews terms and signs contracts electronically using digital signatures on their mobile phone or dealer tablet. The completed loan documentation transmits automatically to the lender's loan servicing platform, where automated clearing house (ACH) pipelines disburse loan proceeds directly to the automotive dealership's commercial account in minutes. By uniting open banking verification, machine-learning collateral valuation, and paperless e-contracting, modern auto lending platforms deliver the speed, security, and accuracy required for modern automotive retail.
Top Trending Reports :
الأقسام
إقرأ المزيد
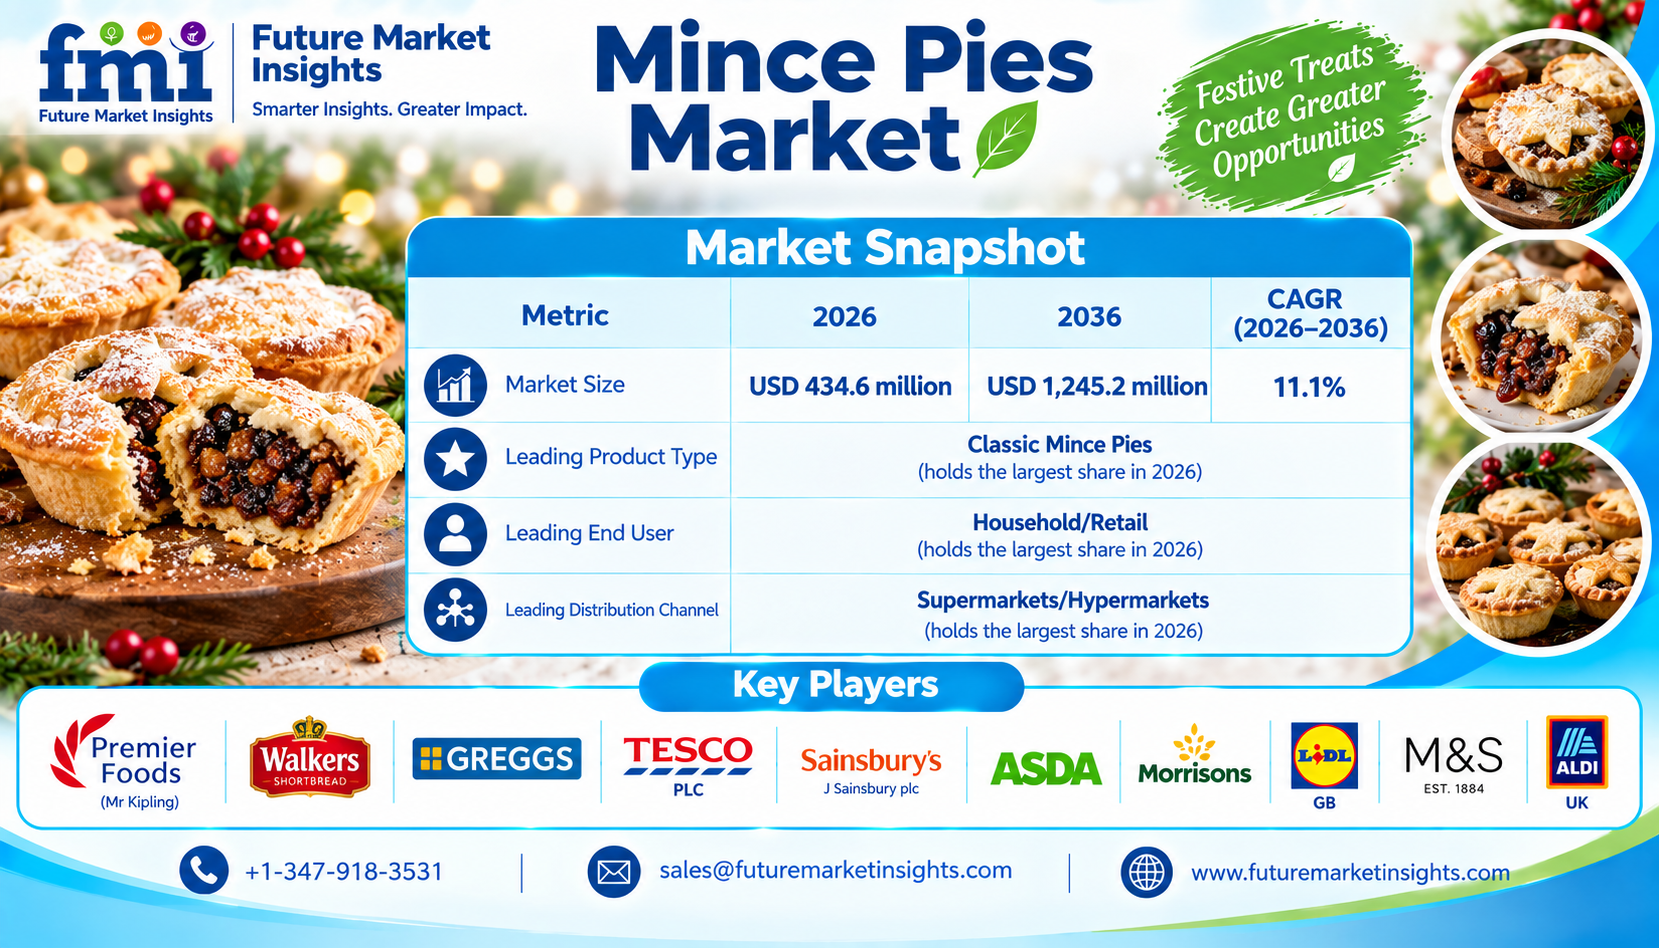
Mince Pies Market as Seasonal Demand and Premium Pastry Variants Extend Festive Consumption The global Mince Pies Market is projected to grow from USD 434.6 million in 2026 to USD 1,245.2 million by 2036, advancing at an 11.1% CAGR during the forecast period, according to the latest research from Future Market Insights (FMI). The market is supported by continued consumer demand for traditional...
Smartwatches have evolved from basic notification devices into multifunctional technologies capable of tracking physical activity and selected health-related metrics. This evolution is playing an important role in the expansion of the Wearable Tracking Devices Market. According to Market Research Future, the industry is projected to reach USD 28.33 billion by 2035 from USD 10.48 billion in...
Gram staining is one of the oldest and most enduring techniques in microbiology. Developed by Hans Christian Gram in 1884, it remains a first-line method for classifying bacteria and guiding treatment decisions. The technique differentiates bacteria into gram-positive and gram-negative based on cell wall structure, providing rapid information that helps clinicians choose appropriate antibiotics...
Market Overview The peripheral artery disease market is being significantly propelled by the global diabetes epidemic, which substantially increases PAD risk among affected populations. Over 30% of diabetic patients develop peripheral artery disease, creating substantial treatment demand as diabetes prevalence continues rising worldwide. The Peripheral Artery Disease Market continues expanding...
According to Market Research Future, the Lithium silicon batteries market was valued at USD 10.26 billion in 2024 and is projected to reach USD 188.32 billion by 2035, expanding at a CAGR of 30.28% during the forecast period. This extraordinary growth reflects the transformative potential of silicon anode technology in delivering significantly higher energy density than conventional...